United States-Australia Income Tax Treaty
The United States-Australia Income Tax Treaty is a cornerstone agreement that facilitates seamless economic collaboration by ensuring fair taxation...
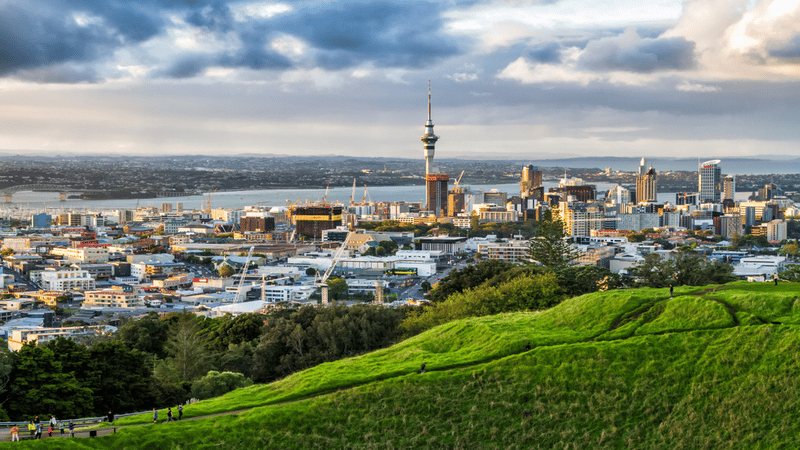
The United States–New Zealand Income Tax Treaty serves as a vital framework for cross-border commerce and investment, establishing clear rules to mitigate the burden of double taxation for cross-border entities and individuals. Signed to promote bilateral trade and financial integration, the convention clarifies tax jurisdictions between the Internal Revenue Service (IRS) and New Zealand’s Inland Revenue Department (IRD). By defining key concepts such as tax residency, permanent establishment, and taxable presence, the agreement reduces barriers to trade and provides a predictable fiscal environment for entities operating in both jurisdictions.
At the core of the treaty are relief mechanisms designed to prevent dual taxation on various income streams, including corporate profits, personal services, dividends, interest, and royalties. Through reduced withholding tax rates and foreign tax credit provisions, taxpayers can offset taxes paid in one country against liabilities in the other. Furthermore, the protocol incorporates a Limitation on Benefits (LOB) clause to prevent treaty shopping, ensuring that only qualified residents and bona fide commercial enterprises enjoy the reduced withholding rates and administrative benefits provided by the agreement.
Navigating the interplay between U.S. citizenship-based taxation and New Zealand’s residence-based tax system requires a comprehensive understanding of these treaty provisions. As cross-border remote work, venture capital investments, and multinational expansions between the two nations continue to grow, compliance with reporting mandates such as FBAR, FATCA, and local IRD requirements becomes critical. This article examines the structure, key provisions, and practical applications of the U.S.–New Zealand Tax Treaty, offering an analysis of how individuals and corporations can optimize their international tax posture while maintaining full regulatory compliance.
Signed in 1982 and updated by a major protocol in 2008, the United States–New Zealand Income Tax Treaty provides the framework for bilateral commerce between the two nations. Designed to foster direct investment and facilitate trade across the Pacific, the convention clearly delineates taxing authority between both tax authorities. The treaty provides precise rules for determining permanent establishment, setting bright-line duration thresholds for construction projects and service provision to prevent unexpected local tax liabilities for foreign enterprises.
A core feature of the agreement is its modern withholding tax framework, significantly reducing source-country taxation on passive income derived from international activities. Under the modified protocol, withholding rates on qualifying intercompany dividends drop to as low as 0%, while standard dividend rates are capped at 15%. Furthermore, interest and royalty payments between the two jurisdictions benefit from reduced withholding tax caps (typically 10% and 5%, respectively), reducing withholding tax costs associated with international transactions.
Compliance requires taxpayers to reconcile the U.S. citizenship-based tax system with New Zealand's residence-based approach. The treaty provides mechanisms that help coordinate reporting and foreign tax credits across both jurisdictions. The treaty also includes provisions addressing pension distributions, social security payments, and temporary workers, while foreign tax credit mechanisms help prevent overlapping tax obligations. Supported by active FATCA financial information exchange between the IRS and the IRD, multinationals and individual taxpayers must coordinate their filings, such as IRS Form 8833 treaty disclosures alongside local IRD declarations, to ensure tax efficiency and full regulatory compliance.
The United States and New Zealand maintain a strong economic relationship supported by trade, investment, and services activity across the Asia-Pacific region. As a prime destination for high-value Kiwi exports and a major source of foreign direct investment (FDI), the U.S. market supports economic activity across technology, creative industries, and logistics.
1. Trade Dynamics & Bilateral Balance
2. Key Sectors & Primary Commodities
Impact of the U.S.–New Zealand Tax Treaty on Business Collaboration
The U.S.–New Zealand Income Tax Treaty fundamentally accelerates corporate expansion by establishing clear operational definitions for physical and digital business presence. By setting precise duration thresholds for permanent establishments, such as service provisions or construction projects exceeding specific time limits, the agreement allows U.S. technology providers, agricultural tech firms, and engineering enterprises to undertake long-term commercial projects in New Zealand without triggering unexpected entity-level corporate tax liabilities. This legal predictability removes arbitrary tax costs, encouraging cross-border joint ventures and long-term commercial relationships.
Beyond operational presence, the treaty streamlines capital flows and transfer pricing frameworks between the two jurisdictions, fostering strategic investments and mergers between American and Kiwi companies. With clear guidelines under Article 9 governing transactions between associated enterprises, multinational groups can structure intercompany pricing, management fees, and intellectual property licensing without facing duplicate taxation on corporate earnings. Reduced withholding tax burdens further incentivize U.S. venture capital and private equity firms to back innovative New Zealand companies, facilitating capital deployment into tech hubs like Auckland and Wellington.
To sustain long-term enterprise partnerships, the treaty establishes a dispute-resolution mechanism known as the Mutual Agreement Procedure (MAP). Handled directly by competent authorities at the IRS and New Zealand's Inland Revenue Department (IRD), MAP offers a dedicated channel to resolve tax interpretation conflicts, audit adjustments, and transfer pricing disputes outside costly litigation. Coupled with bilateral tax information exchange and anti-discrimination protections, this cooperative mechanism assures international business executives that both jurisdictions maintain a fair, transparent, and stable commercial environment.
Understanding how specific income streams are categorized and taxed under the United States–New Zealand Income Tax Treaty (as updated by the 2008 Protocol) is essential for optimizing multinational structures, eliminating overlapping tax exposure, and maintaining full reporting compliance in each country.
Under Article 10, dividends distributed by a company in one contracting state to a beneficial owner in the other may be taxed in both states, but host-country Non-Resident Withholding Tax (NRWT) is subject to strict caps:
Practical Scenario:
A U.S. parent company holds a 25% voting interest in an active Auckland-based software firm. When the New Zealand entity pays a dividend, the domestic non-resident withholding rate is reduced from standard levels to 5% under the treaty. The U.S. parent then claims a U.S. foreign tax credit (FTC) to offset foreign taxes paid against its U.S. corporate tax liability.
Article 11 caps the general source-country withholding tax on cross-border interest payments at 10%. However, the 2008 Protocol introduced a full exemption (0% WHT) for interest paid to qualifying financial institutions, banks, or enterprise lending entities.
Practical Scenario:
A Wellington startup secures a corporate loan from a U.S. commercial bank. Rather than being subject to standard non-resident interest withholding tax rates, the interest payments qualify for the 0% treaty exemption for financial institutions, allowing full debt-service transfers without local tax deductions at source.
Royalties derived from licensing patents, trademarks, technical know-how, or software copyrights are subject to a capped source-country withholding tax of 5% under the treaty. (Note: The protocol specifically excludes payments for leased commercial or industrial equipment from the definition of royalties).
Practical Scenario:
A New Zealand enterprise licenses proprietary software from a Silicon Valley provider. Under New Zealand domestic law, cross-border royalty payments carry a 15% withholding rate. Applying Article 12 lowers the withholding rate to 5%, significantly reducing the overall withholding tax burden on technology licensing.
Capital gains derived from the alienation of assets are generally taxable only in the seller’s country of residence. Host-country taxation applies only under specific statutory exemptions:
Practical Scenario:
A U.S. investor disposes of shares held in a New Zealand commercial technology enterprise that owns no real estate. Under Article 13, New Zealand cannot assess capital gains tax on the transaction, leaving primary tax jurisdiction exclusively to the United States.
Active commercial profits generated by an enterprise of one nation are taxable only in its home country unless business is carried out in the host nation through a Permanent Establishment (PE). A PE is triggered by fixed physical operations or specific duration thresholds (e.g., building sites or construction projects lasting more than 12 months, or natural resource exploration exceeding 6 months).
Practical Scenario:
An American consultancy provides short-term project management services to Christchurch clients remotely without maintaining a physical office or exceeding local time thresholds. Because no PE is created, New Zealand cannot levy corporate income tax on the project earnings.
| Income Category / Stream | Standard U.S. Domestic Rate | Standard NZ Domestic Rate (NRWT) | Treaty Reduced WHT Rate |
| Major Corporate Dividends (≥ 80% Ownership) | 30% | 30% | 0% (Subject to LOB) |
| Direct Dividends (≥ 10% Ownership) | 30% | 30% / 15% (Imputed) | 5% |
| Portfolio Dividends (<10% Ownership) | 30% | 30% / 15% (Imputed) | 15% |
| General Interest Income | 30% | 15% (or 2% AIL) | 10% |
| Bank / Financial Institution Interest | 30% | 15% | 0% |
| Royalties & Software Copyrights | 30% | 15% | 5% |
| Capital Gains (Non-Real Estate Shares) | Standard CGT | Exempt / Trading Tax | Exempt in Host Country |
Understanding treaty provisions is only the first step; executing rigorous compliance and maintaining comprehensive documentation is where bilateral strategies succeed or fail. Missteps in administrative reporting or missing documentation can result in immediate loss of treaty benefits, triggering maximum statutory withholding taxes and costly administrative disputes.
Accessing reduced withholding rates on payments between the U.S. and New Zealand requires formal verification of tax residency and beneficial ownership before funds are disbursed:
Payer entities operating as withholding agents in either country bear legal responsibility for correctly applying treaty rates. If a withholding agent disburses dividends, interest, or royalties without holding valid, unexpired tax residency documentation on file, they are legally mandated to deduct standard domestic statutory rates (30% in the U.S. or standard NRWT rates up to 30% in New Zealand). Recovering overwithheld taxes retroactively requires filing complex refund claims with the IRS or the IRD, creating significant cash flow delays.
To eliminate dual taxation, taxpayers must meticulously document host-country tax payments to support claims on home-country annual returns:
When a taxpayer takes a position that a U.S.–New Zealand treaty provision overrides or modifies an Internal Revenue Code rule, federal law requires formal disclosure to the IRS:
The United States–New Zealand Income Tax Treaty serves as an important framework for enterprises and investors navigating international commerce across the Pacific Rim. By defining clear rules for tax residency, permanent establishment thresholds, and source-country withholding rates, the agreement significantly reduces double taxation risks and establishes a predictable fiscal framework. However, simply relying on the existence of the treaty is insufficient; unlocking its full economic value requires precise alignment between corporate operations, entity structures, and bilateral reporting mandates.
As commercial activity between the U.S. and New Zealand continues to expand in high-growth sectors such as technology, venture capital, and agriculture, the administrative burden of maintaining compliance has intensified. Both the U.S. and New Zealand tax authorities strictly enforce documentation requirements, from executing Limitation on Benefits (LOB) certifications on IRS Form W-8BEN-E to submitting treaty-based disclosures via IRS Form 8833. Organizations that proactively manage these obligations safeguard their access to reduced withholding rates on dividends, interest, and royalties while insulating themselves from costly audit exposure.
Ultimately, successful multinational tax planning hinges on treating treaty compliance not as an annual administrative task, but as a core component of global business strategy. By aligning intercompany pricing, monitoring employee service presence, and utilizing foreign tax credit mechanisms, multinational corporations and investors can optimize their effective global tax rates. Maintaining thorough documentation and engaging competent authorities when disputes arise ensures long-term operational resilience and sustainable growth in both jurisdictions.
Navigating the U.S.–New Zealand Income Tax Treaty requires technical precision and proactive planning. At H&CO, our international tax specialists assist multinational businesses, investors, and individual taxpayers in optimizing international tax positions while maintaining full compliance with both the IRS and Inland Revenue Department (IRD).
Whether expanding into New Zealand, deploying capital, or managing dual-residence tax duties, H&CO provides end-to-end guidance to reduce global tax drag and support your international expansion objectives.
The fundamental goal of the agreement is to prevent overlapping tax liabilities on individuals and corporate entities that generate income across both jurisdictions. By establishing clear rules for tax residency, permanent establishment, and maximum allowable source-country withholding rates, the treaty reduces financial barriers to bilateral trade, protects investors from redundant tax liabilities between the IRS and New Zealand’s Inland Revenue Department (IRD), and creates a predictable legal environment for cross-border investment.
The treaty significantly lowers standard domestic non-resident withholding tax rates on cross-border dividend distributions. Under Article 10, dividend withholding tax is capped at 0% for qualifying corporate parent entities holding an 80% or greater voting stake for at least 12 months, 5% for direct corporate investments holding at least 10% voting power, and 15% for portfolio investments or individual shareholders.
Under the modified protocol, general cross-border interest payments are capped at a maximum 10% source-country withholding tax, while an exemption (0% rate) applies to interest paid to qualifying financial institutions and banks. For intellectual property royalties, software licensing, and patents, the source-country withholding rate is limited to 5%, significantly reducing the tax burden on technology transfers and commercial licensing between both nations.
The treaty incorporates a stringent Limitation on Benefits (LOB) provision under Article 16, requiring entities claiming treaty benefits to prove a genuine economic connection to either the United States or New Zealand. Corporate entities must demonstrate that they meet specific tests, such as being publicly traded, meeting active trade or business criteria, or passing ownership and base-erosion thresholds, on documentation like IRS Form W-8BEN-E before qualifying for lower withholding rates.
A U.S. company creates a Permanent Establishment in New Zealand if it maintains a fixed place of business, such as an office or branch, or engages in specific physical activities exceeding temporal limits. Under Article 5, construction or building projects lasting more than 12 months or technical and advisory services rendered on-site for more than 183 days within any 12-month period trigger a PE, subjecting the attributable local income to New Zealand corporate income tax filings.
Taxpayers utilize foreign tax credit (FTC) mechanisms in their home country to offset income taxes legally paid to the host nation. U.S. citizens and corporations claim credits for tax paid to the IRD by submitting IRS Form 1116 (for individuals) or Form 1118 (for corporations) on their federal tax returns. Conversely, New Zealand tax residents offset U.S. federal taxes paid against their domestic tax liabilities under Subpart LJ of the New Zealand Income Tax Act 2007.
To receive reduced withholding tax rates on dividends, interest, or royalties originating in the U.S., New Zealand individuals must provide the U.S. payer with a fully completed IRS Form W-8BEN, while corporate entities must submit Form W-8BEN-E prior to disbursement. These certificate forms document non-U.S. tax status, establish beneficial ownership, and formally certify compliance with the treaty’s Limitation on Benefits clauses.
IRS Form 8833 (Treaty-Based Return Position Disclosure) must be attached to a U.S. federal tax return whenever a taxpayer takes a position that a U.S.–New Zealand treaty provision overrides, modifies, or grants exemption from standard Internal Revenue Code regulations. Failing to file Form 8833 when claiming treaty positions, such as overriding Permanent Establishment rules or claiming capital gains exemptions, can result in statutory penalties of $1,000 for individual filers and $10,000 for C corporations.
Under Article 13, capital gains derived from the sale of personal property, shares, or securities are generally exempt from taxation in the host country and are taxed exclusively in the seller’s country of residence. Host-country taxation applies only in narrow exceptions, such as the disposition of real property (immovable property) located in that country, shares in land-rich entities where real estate makes up the majority of asset value, or personal property attached to a local Permanent Establishment.
When conflicting interpretations of tax residency or unilateral audit adjustments by the IRS or IRD result in double taxation, taxpayers can request assistance under Article 24 via the Mutual Agreement Procedure (MAP). This administrative channel allows the competent tax authorities of both countries to negotiate directly to resolve tie-breaker residence cases, transfer pricing disputes, or inconsistent classifications without requiring the taxpayer to engage in litigation in court.
The United States-Australia Income Tax Treaty is a cornerstone agreement that facilitates seamless economic collaboration by ensuring fair taxation...
The United States-Canada Income Tax Treaty is a cornerstone for cross-border trade, investment, and cooperation between these two economic giants....
Expanding business operations internationally or managing cross-border assets opens massive growth opportunities, yet it often brings significant...